Most homeowners insurance policies pay for crime scene cleanup insurance claims, but the payout depends on specific policy wording and the type of incident. Many families discover this only after a traumatic event, when a claims adjuster starts asking questions they were not prepared to answer.
This post breaks down which policies pay, what triggers a denial, and how to file a claim that gets approved. You will learn the exact language to look for and the exceptions that catch people off guard.
Does Homeowners Insurance Cover Crime Scene Cleanup?
Standard homeowners insurance covers crime scene cleanup when the event damages your property. Cleanup falls under the same section that pays for fire or water damage repairs.
The technical term matters here. Insurers classify biohazard remediation as property damage restoration, not medical or funeral expense. That distinction decides which part of your policy responds.
Which Policy Section Pays
Cleanup costs draw from your Dwelling Coverage (Coverage A) for structural damage. Damage to furniture or carpets pulls from Personal Property (Coverage C).
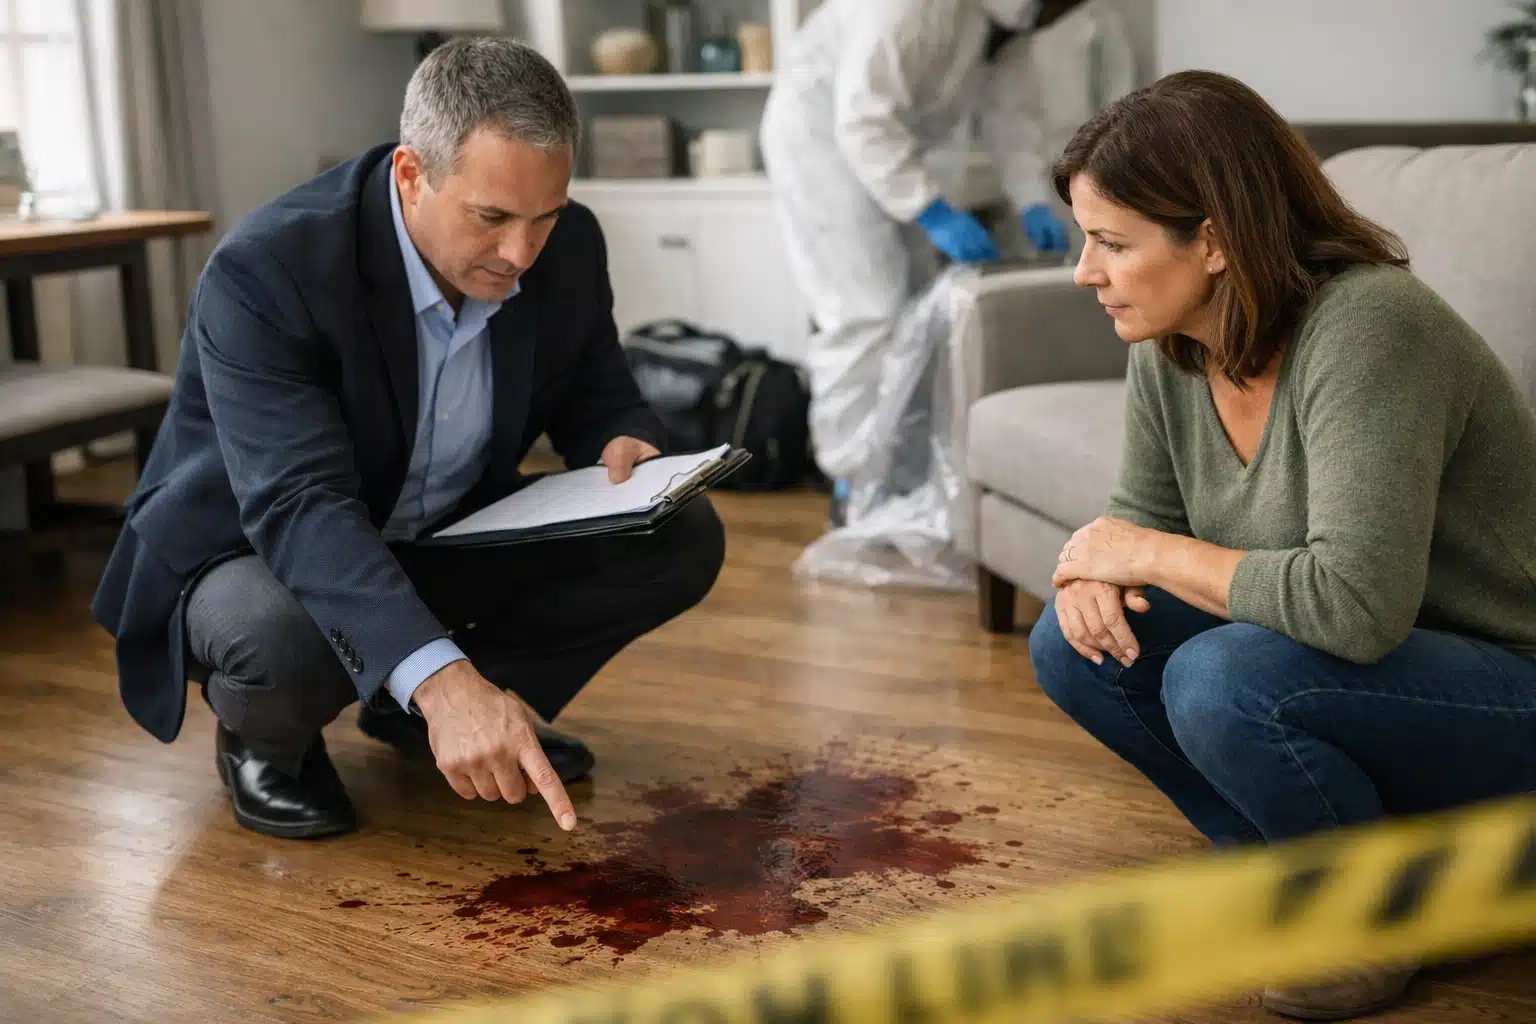
A blood-soaked hardwood floor is a Coverage A claim. A ruined mattress is a Coverage C claim. Adjusters split the estimate between both lines.
Typical Coverage Limits
Most policies cap biohazard cleanup between $2,500 and $10,000 without extra riders. A homicide or unattended death cleanup can exceed $15,000 in a single room.
Check your declarations page for a “trauma scene” or “biohazard” sublimit. Some carriers bury this cap in fine print separate from your main dwelling limit.
Crime Scene Cleanup Insurance Exceptions You Should Know
Policies contain specific exclusions that turn an approved claim into a denial. These clauses catch most people by surprise.
- Intentional acts: If a covered resident caused the harm on purpose, the claim is void.
- Vacant property: Homes empty for 30 to 60 days lose coverage under most vacancy clauses.
- Illegal activity: Damage tied to drug manufacturing or other crimes by the insured gets denied.
- Business use: A rental unit needs a landlord policy, not a standard homeowners plan.
- Pre-existing conditions: Mold or decomposition that spread before you reported it may be excluded.
The Unattended Death Trap
Unattended death cleanup triggers a hidden exception in many policies. If a body decomposes for days, insurers may argue the damage stems from neglect or gradual deterioration.
Gradual damage clauses exclude losses that happen slowly over time. Document the timeline and report the loss the same day you discover it. Delay gives the adjuster grounds to reduce the payout.
Suicide and Coverage
Suicide cleanup is covered under most homeowners policies. The intentional-act exclusion applies to property damage caused on purpose, not to the emotional circumstances of the death.
Some carriers still push back. If denied, ask the adjuster to cite the exact exclusion in writing. Vague denials rarely survive a formal appeal.
How to File a Crime Scene Cleanup Insurance Claim
Filing correctly protects your payout and speeds approval. Follow these steps in order.
- Get the police report number. Insurers require it to verify the event as a covered peril.
- Call your carrier before hiring anyone. Ask for the claim number and your assigned adjuster’s direct line.
- Request the biohazard sublimit in writing. Confirm the dollar cap before work begins.
- Photograph everything. Capture affected rooms, items, and structural damage before any cleaning starts.
- Hire a licensed biohazard remediation company. Verify they carry bloodborne pathogen certification.
- Keep every invoice and disposal manifest. Regulated waste hauling generates paperwork adjusters need.
- Submit a detailed itemized estimate. Line-item bills get approved faster than lump-sum quotes.
Why the Order Matters
Hiring a cleanup crew before calling your insurer can void reimbursement. Some policies require pre-authorization for non-emergency work.
Biohazard cleanup counts as emergency mitigation, but proving that requires documentation. Photos taken before cleanup lock in the scope of loss.
What If You Have No Coverage?
Renters and uninsured homeowners still have paths to pay for cleanup. Do not assume the cost falls entirely on you.
State Victim Compensation Funds
Every state runs a Crime Victim Compensation program funded by criminal fines. These funds reimburse cleanup for violent crimes, including homicide and assault.
Coverage caps vary by state, from $1,000 to over $25,000 for scene cleanup. Apply within the deadline, which runs one to three years depending on the state.
Renters and Landlord Responsibility
Renters insurance covers personal property damage from a crime, not the structure. Structural cleanup falls to the landlord’s dwelling policy.
A tenant’s blood-damaged furniture is a renters claim. Damaged subflooring is the landlord’s responsibility. Clarify this split before signing any cleanup contract.
Choosing a Restoration Company That Bills Insurance Directly
Many biohazard companies bill your insurer directly, so you avoid paying out of pocket. This arrangement removes the burden of fronting thousands of dollars.
Ask any provider these questions before hiring:
- Do you bill insurance carriers directly?
- Are you certified for bloodborne pathogen and trauma cleanup?
- Do you provide itemized estimates that match adjuster expectations?
- Can you supply disposal manifests for regulated medical waste?
- Have you worked with my specific insurance carrier before?
Finding Qualified Providers Near You
Restoration Locator lets you filter listings by biohazard and trauma cleanup capability. Sort by location to find crews that respond fast in your area.
Check reviews on each listing to confirm past clients had smooth insurance billing. A provider familiar with your carrier reduces claim friction.
Documentation That Prevents Claim Denials
Strong records separate approved claims from denied ones. Keep a single folder with every piece of paper.
- Police report with case number and officer contact
- Time-stamped photos of all affected areas
- Death certificate when applicable
- Itemized remediation estimate and final invoice
- Waste disposal manifests for regulated materials
- Written communication with your adjuster
If an adjuster disputes the scope, your photos and manifests settle it. Written records also strengthen any appeal you file later.
Key Takeaways
Homeowners insurance usually pays for crime scene cleanup under dwelling and personal property sections, subject to sublimits and exclusions. Watch for vacancy clauses, gradual-damage denials, and business-use exceptions that block claims. When insurance falls short, state victim compensation funds cover cleanup for violent crimes.
Start your search for a certified biohazard remediation provider that bills insurance directly. Browse Disaster Cleanup & Restoration listings now at https://restorationlocator.com.